
Switzerland can no longer be content with simply inventing things
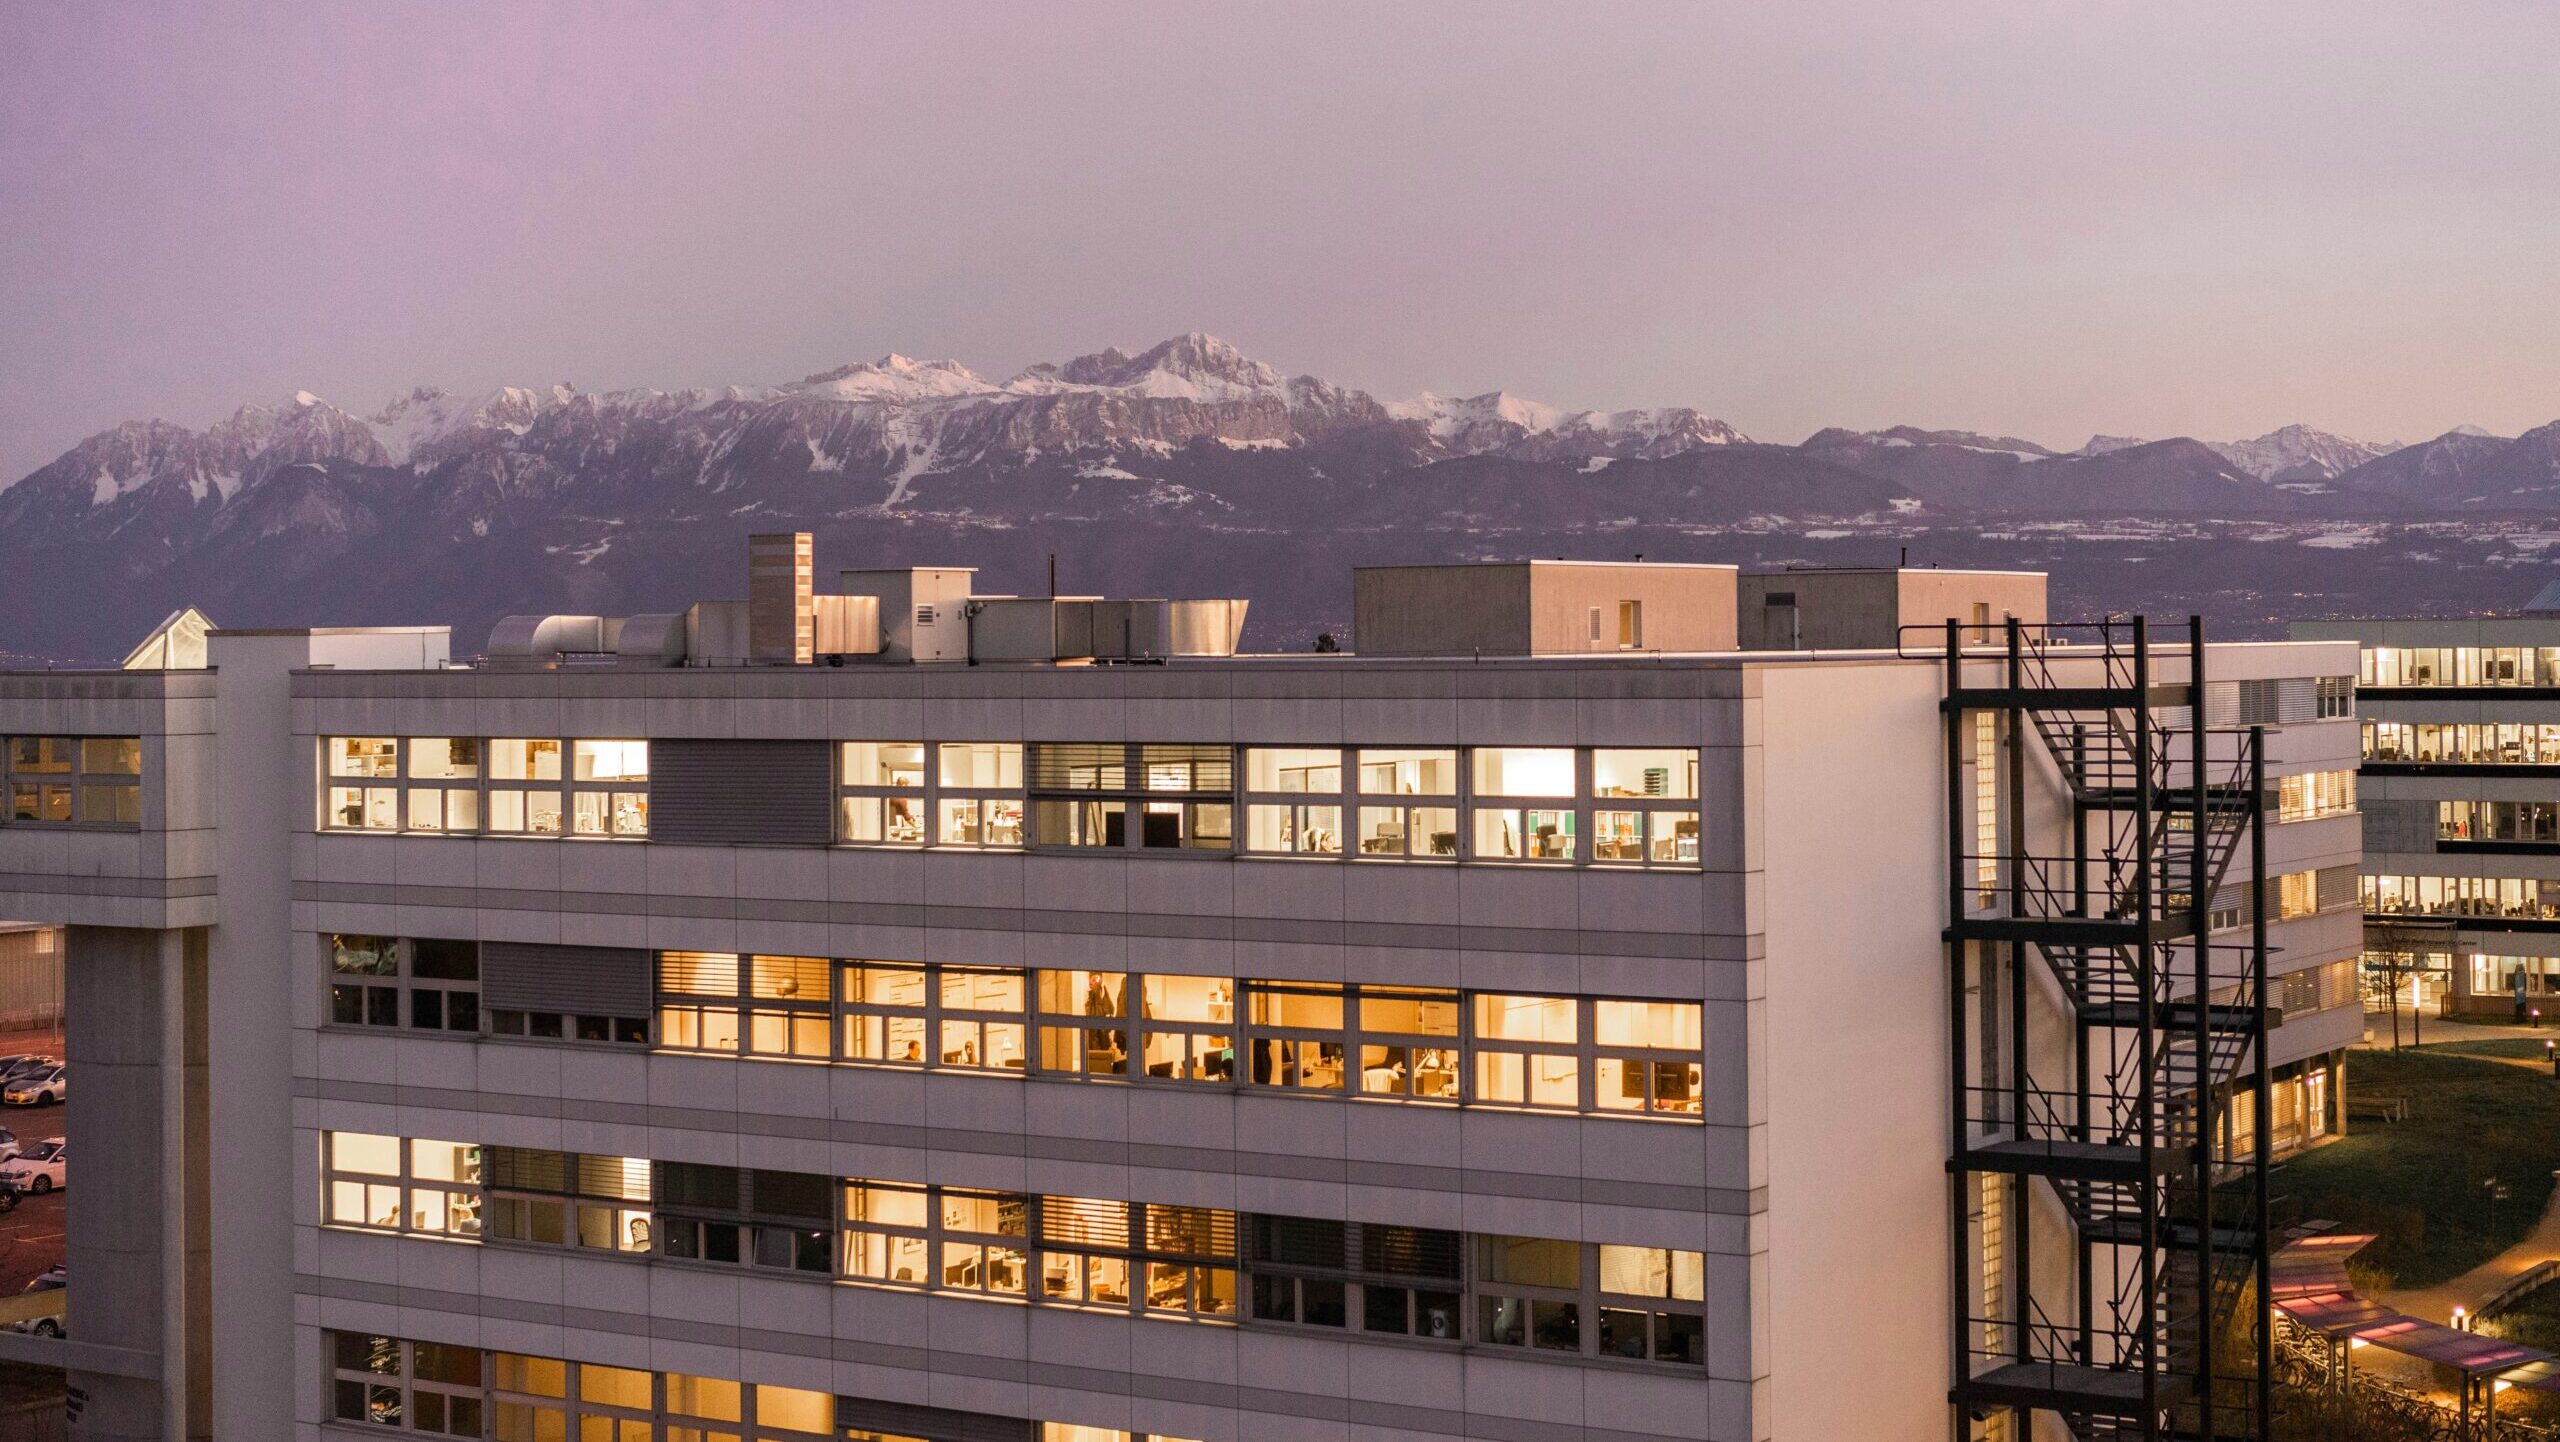
The EPFL campus in Lausanne. Photo: Baptx via Unsplash
Ranked at the top of the global innovation rankings, Switzerland’s innovation ecosystem excels at creating companies. In the age of artificial intelligence, helping these companies grow at home will depend on three resources: capital, computing power, and trust.
Few countries innovate as much as Switzerland. It has topped the global innovation rankings for more than fifteen years and, in 2025, filed more European patent applications per capita than any other country except Liechtenstein. The economist Joseph Schumpeter, however, distinguished between invention—which is a matter of knowledge—and innovation, which requires a company to bring the idea to market. It is in this gap that part of our prosperity is determined.
When it comes to Swiss innovation, the numbers look impressive at first glance. In 2025, the Swiss Federal Institute of Technology in Lausanne (EPFL) saw a record 39 startups emerge; the Swiss Federal Institute of Technology in Zurich (ETH), 46. Five years after their founding, 70 to 90% of these spin-off are still in business. While this is certainly cause for celebration, this rate should also give us pause. In the innovation economy, failure is not an anomaly—it is the price of taking bold risks. If nearly all startups survive, it also means that their business models take few risks.
Many of these spin-off grow into solid, profitable, and prudent small and medium-sized enterprises. Too few seek to become global leaders, with all that this entails in terms of capital, speed, and boldness. The challenge has therefore shifted: Switzerland knows how to create companies, but struggles to help them grow within the country.
Helping what we invent grow
Artificial intelligence makes this an urgent issue: three factors determine the fate of a startup—capital, computation, and trust. First, capital. In the deeptech In Switzerland, more than 80% of the funds raised in financing rounds ranging from $15 million to $100 million come from abroad, compared with a European average of 60%. In 2024, 30 of the 41 acquisitions of Swiss startups were carried out by foreign buyers. Neither acquisitions nor foreign capital are inherently bad; the problem arises when the value generated by public effort is capitalized elsewhere.
However, our pension funds manage more than 1,200 billion francs: 1% of these savings, gradually invested in diversified portfolios of young Swiss companies, would represent more than four times the venture capital invested in Switzerland in 2025. We propose this without imposing any obligations on the funds, whose fiduciary duty remains fully intact: the goal is to align our savings with the growth that our research makes possible.
Computing: A Strategic Infrastructure
Next, the computing. Thanks to the Alps supercomputer, EPFL, ETH Zurich, and the Swiss Center for Scientific Computing were able to train «Apertus,» a fully open-source language model. However, a single Texas campus is designed to reach a power output of 1.2 gigawatts, while the capacity currently available across all Swiss commercial data centers totals approximately 340 megawatts. We won’t win the race for scale.
In January 2025, a U.S. regulation—which was repealed before it took effect—had classified Switzerland among the countries whose access to advanced chips would have been restricted. Imported capacity remains conditional capacity. Sovereignty, in this context, does not mean self-sufficiency: it is the ability to choose one’s dependencies rather than simply enduring them. Computing has become an infrastructure, like energy or rail: it requires a long-term vision, private capital alongside public funds, and open access for startups.
Trust as a Comparative Advantage
Trust remains an issue. Hospitals, businesses, and government agencies are understandably hesitant to entrust their data to opaque systems subject to other jurisdictions. Switzerland can become—if not the largest, then the most essential—thanks to open models, where anyone can examine the sources and reproduce the results, a stable legal framework, and data protection recognized by the European Union. Just as it has long provided a foundation of trust for diplomacy, it can now do the same for data. However, a clear and proportionate regulatory framework is still needed: if it is confusing or unstable, it will primarily burden the smallest players.
On June 21 and 22, 2027, Geneva will host the next international summit on artificial intelligence, focused on innovation and trust. This is a rare opportunity to bring together the worlds of research, finance, and regulation—three fields that, in our region, still do not engage with one another nearly enough. Geneva’s financial center is already attracting new players: the technology company Freedom24, the European arm of Freedom Holding Corp., announced in September that it views Switzerland as a market of long-term strategic interest and is exploring opportunities to establish a presence in Geneva.
The arrival of such players is good news. But their capital still needs to align with what our universities are producing. Switzerland has become one of the world’s leading laboratories. It now must decide whether the innovations it creates will also thrive at home.
Nicolas Ramseier is president of the Geneva Center for Neutrality
This topic will be explored in greater depth on Friday, October 30, at the «From Lab to Market» conference at the Société de Lecture in Geneva.
You have just read exclusive, open-access content. Debates, analyses, cultural news: subscribe to support us and get access to all our content!

You'll also like
 French
 German
 English
Leave a comment